Healthcare workers in the United States are increasingly feeling the strain of rising health insurance costs, with some choosing to go uninsured as premiums surge and pandemic-related subsidies expire, according to data and interviews reported by KFF Health News. This trend not only affects healthcare professionals but also reverberates through small medical practices and their patients.
What Happened
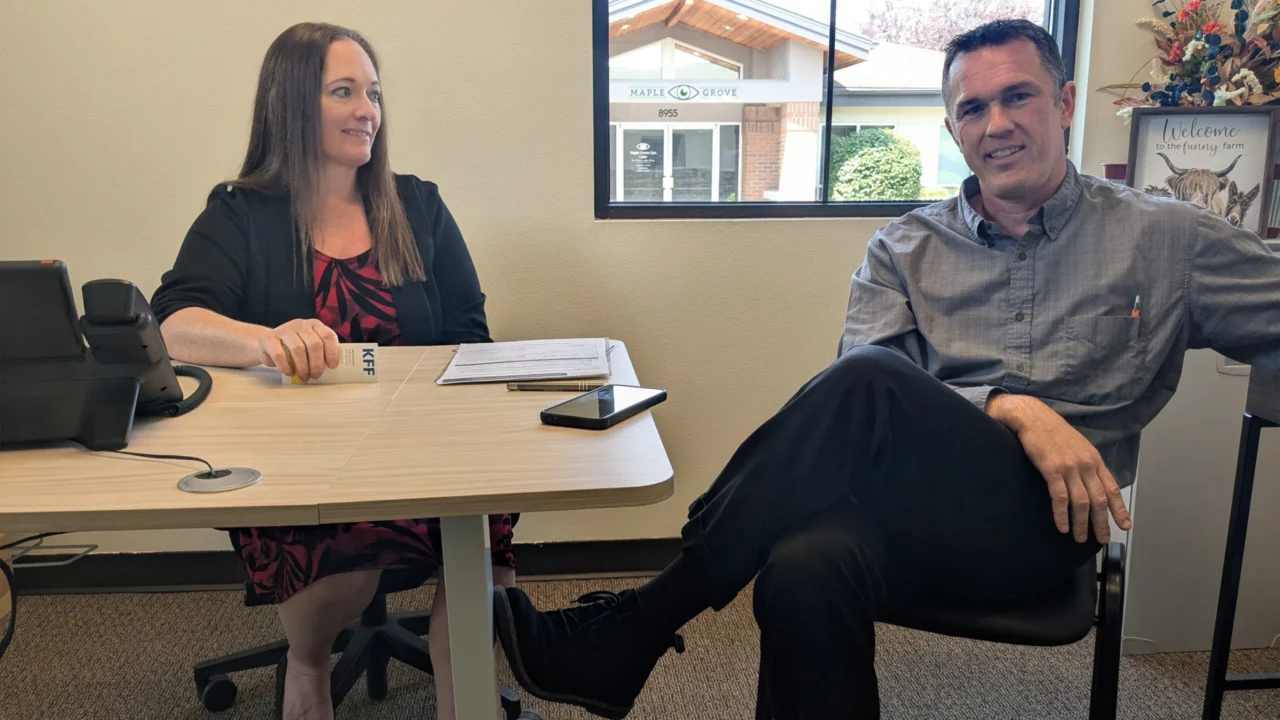
Joshua and Ashley Durham, who operate a family medicine practice in Boise, Idaho, recently made the difficult decision to forgo health insurance for themselves and their two children after a sharp rise in monthly premiums. The Durhams previously purchased coverage through the Affordable Care Act (ACA) marketplace, but their premiums jumped by several hundred dollars to nearly $1,600 per month for similar coverage in 2024. Opting instead to pay for medical expenses out-of-pocket, they have been relying on a health savings account with around $50,000 saved over several years.
The Durhams’ experience reflects a broader issue identified in a recent analysis of 2024 American Community Survey data by KFF: 7% of healthcare workers nationwide were uninsured, compared with 11% of all adults under age 65. While doctors remain least likely to be uninsured (around 2%), the rising cost of coverage is significantly impacting other healthcare professionals and small employers.
The expiration of expanded ACA marketplace tax credits, enacted during the COVID-19 pandemic, has further exacerbated the problem for workers at small businesses, including many in independent medical practices. Although subsidies remain available for low-income individuals, nearly half of marketplace enrollees work for small businesses or are self-employed, often facing steep premium increases now that these pandemic-era credits have ended.
Key Facts
The Congressional Budget Office projects the number of uninsured people in the U.S. could increase by approximately 15 million over the next decade due to the loss of expanded ACA subsidies and substantial budget cuts from legislation like the One Big Beautiful Bill Act.
Employers anticipate that health insurance costs will rise an additional 8.2% in 2027, placing further financial pressure on workers and small medical practices.
Healthcare workers interviewed reported premium increases ranging from around $700 to $1,500 monthly for family coverage. Samantha LeGault, a nurse practitioner with Crohn’s disease and family members with other medical conditions, said her premiums doubled this year to $1,500 monthly, now consuming about one-fifth of her income.
Healthcare executives and clinicians alike say such cost surges are forcing difficult trade-offs, including skipping dental insurance, deferring care, and shifting to public schooling to reduce expenses.
What This Means
Rising health insurance costs are beginning to severely challenge the healthcare workforce, a sector traditionally better insured than most others. For many healthcare workers, the dilemma is stark: pay soaring premiums out of strained budgets or risk going uninsured and facing potentially devastating medical bills. This economic squeeze not only threatens their personal financial security but may impact workforce stability and patient care quality.
Small healthcare practices, which constitute a sizable portion of medical care providers, are particularly vulnerable. The rising insurance expenses undermine their ability to offer comprehensive employee benefits or could lead practices to reduce coverage, offer minimal plans, or increase wages instead, shifting costs onto workers.
The potential increase in uninsured healthcare workers—many of whom have chronic conditions or dependents with medical needs—could exacerbate gaps in primary care access and strain public health resources. Moreover, healthier individuals opting out of insurance pools may drive premiums even higher for those remaining insured, creating a vicious cycle of escalating costs.
Background
The ACA introduced expanded premium tax credits during the COVID-19 pandemic to help make insurance more affordable. These subsidies, which significantly reduced premium costs for many individuals, were not renewed by the Republican-led Congress in 2023.
This policy change has had an outsized impact on workers at small businesses and self-employed individuals, groups that represent a large share of healthcare marketplace enrollees. According to the Association for Independent Medicine, insurance premiums for small medical practices have reached levels they consider unsustainable.
Analysis
Jack Dillon, executive director of the Association for Independent Medicine, described the rise in premium costs as “astronomical” and questioned the value of coverage at such levels. Bioethicist Arthur Caplan noted that with increasing barriers to regular healthcare access, more people may rely on family members for medical care, prompting reconsideration of professional ethical guidelines discouraging self-treatment.
Healthcare workers like nurse practitioner LeGault illustrate the personal toll: difficult financial choices, compromised care decisions, and heightened stress linked to medical expenditures that can consume significant shares of household income.
What Remains Unclear
It is uncertain how many more healthcare workers will choose to forgo insurance as costs continue to climb, and whether small practices will adapt by reshaping employee benefits or wages to sustain operations. The long-term effects on healthcare access, workforce retention, and patient outcomes remain to be seen.
What Comes Next
Employers are preparing for ongoing premium increases, with projections of an 8.2% rise in 2027. Policymakers have yet to reinstate expanded ACA subsidies, and healthcare industry advocates continue to call attention to the affordability crisis facing both providers and patients.
Sources
This article is based on reporting and publicly available information from the following sources:
Read more Health & Public Health stories on Goka World News.